

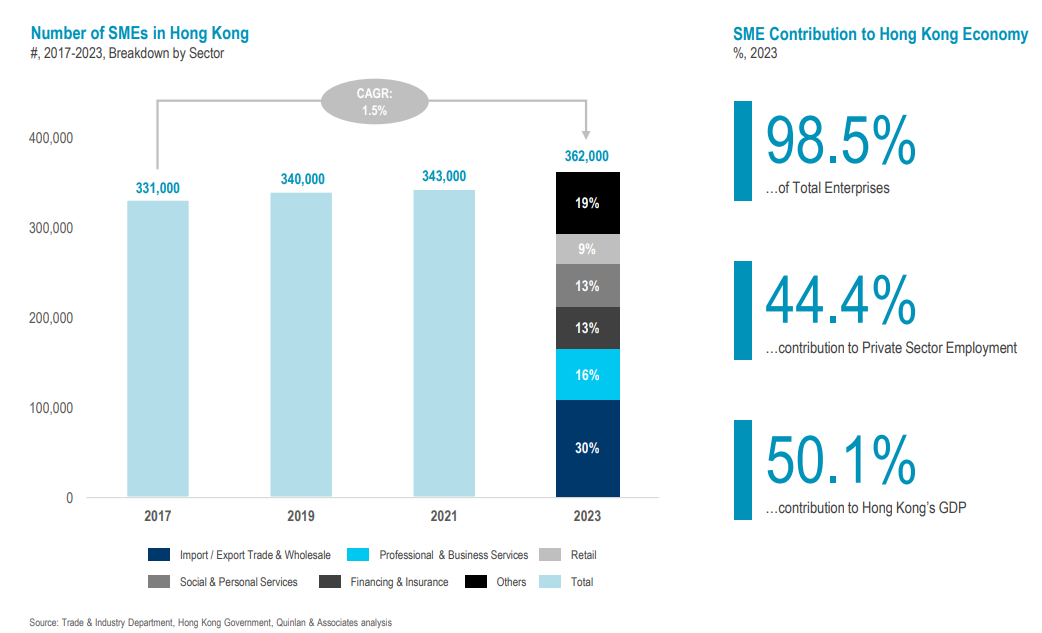
The vibrant economy of Hong Kong is significantly bolstered by small and medium-sized enterprises (SMEs), which constitute nearly 99 percent of its business landscape and are central to the SME lending sector.

With over 362,000 SMEs as of the end of 2023, these entities contribute approximately 44 percent of private-sector employment and 50 percent of the city’s GDP.
Despite their substantial economic impact, SMEs in Hong Kong face considerable challenges in securing necessary credit, highlighting a persistent gap that has implications for growth and innovation.
The SME lending landscape in Hong Kong
SMEs in Hong Kong exhibit diverse financing needs, ranging from covering daily operational costs to supporting expansion efforts through trade finance or franchising.
Despite an apparent demand for credit, stagnant loan balances since 2018 reflect an under-served sector struggling with accessibility to funds.
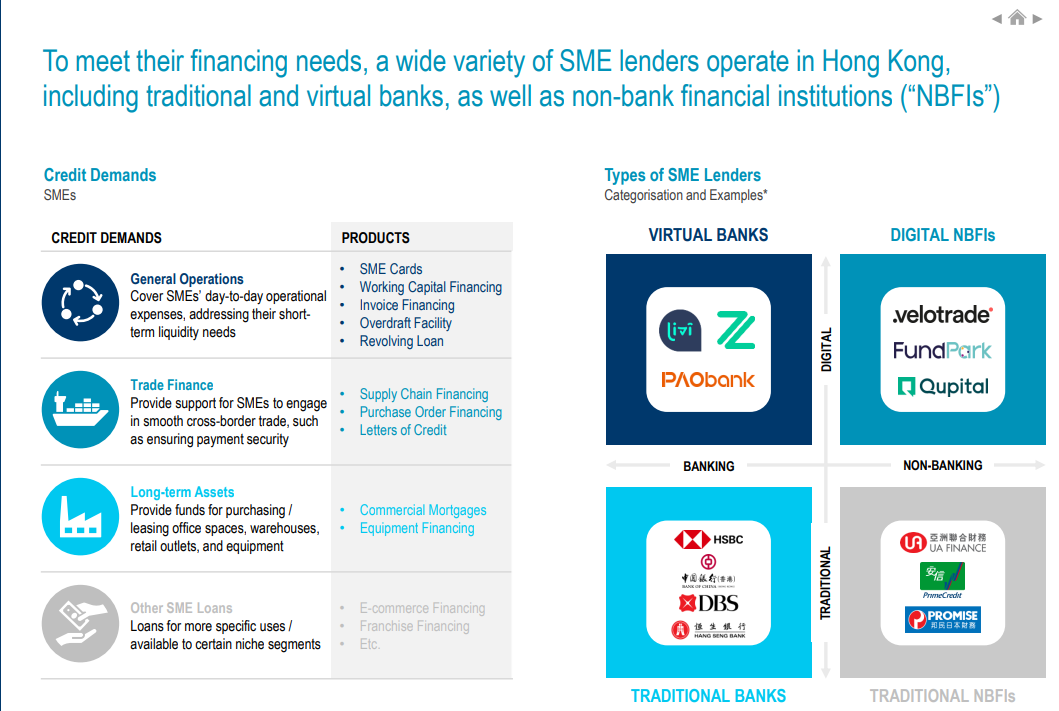
A mix of traditional banks, virtual banks, and non-banking financial institutions (NBFIs) forms the lending landscape. Yet, operational inefficiencies and stringent lending criteria often lead to a mismatch between SME needs and available financial products.
Traditional banks like HSBC, Hang Seng, and Standard Chartered are the primary SME lenders, offering comprehensive product suites, from working capital financing to trade finance.
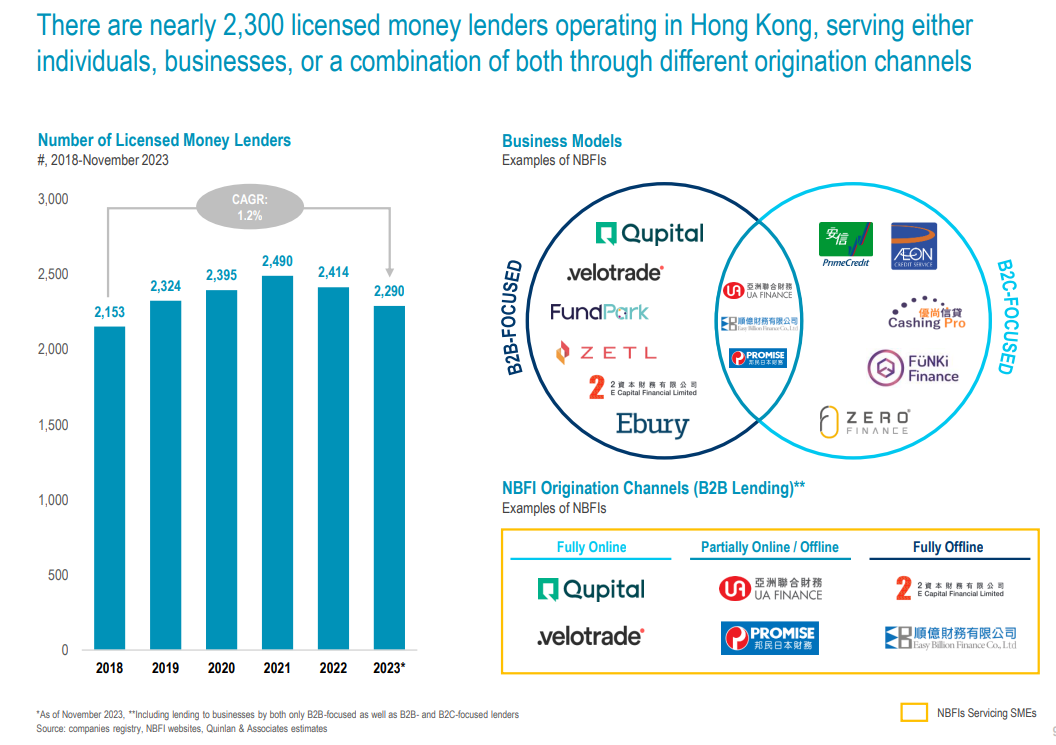
Six of the eight virtual banks in Hong Kong target SMEs exclusively or in conjunction with their retail offerings. PAOBank and Ant Bank are SME-focused, extending services across import/export and hospitality sectors. Livy Bank, ZA Bank, Fusion Bank, and Airstar Bank also provide SME banking.
Notable digital NBFIs serving Hong Kong SMEs, such as Qupital, Velotrade, FundPark and Zetl, are in fierce competition with more established players like UA Finance and Promise.
SME lending pain points
In-depth interviews by Quinlan & Associates highlight major operational pain points hampering the SME lending experience.
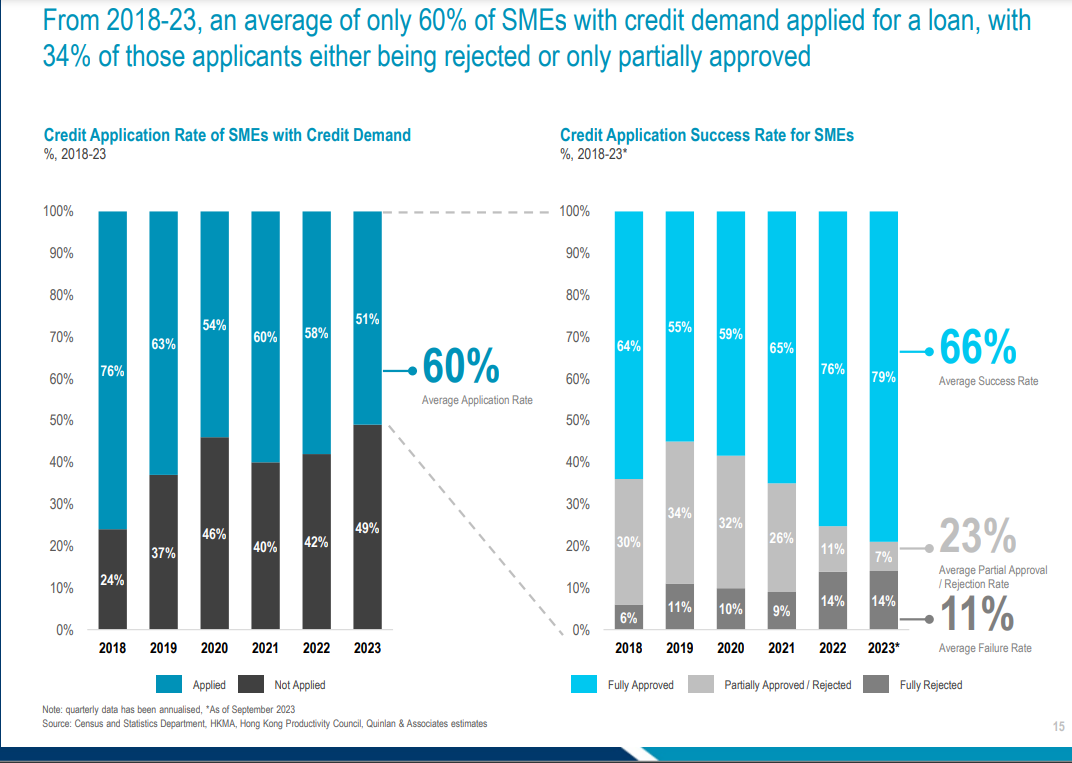
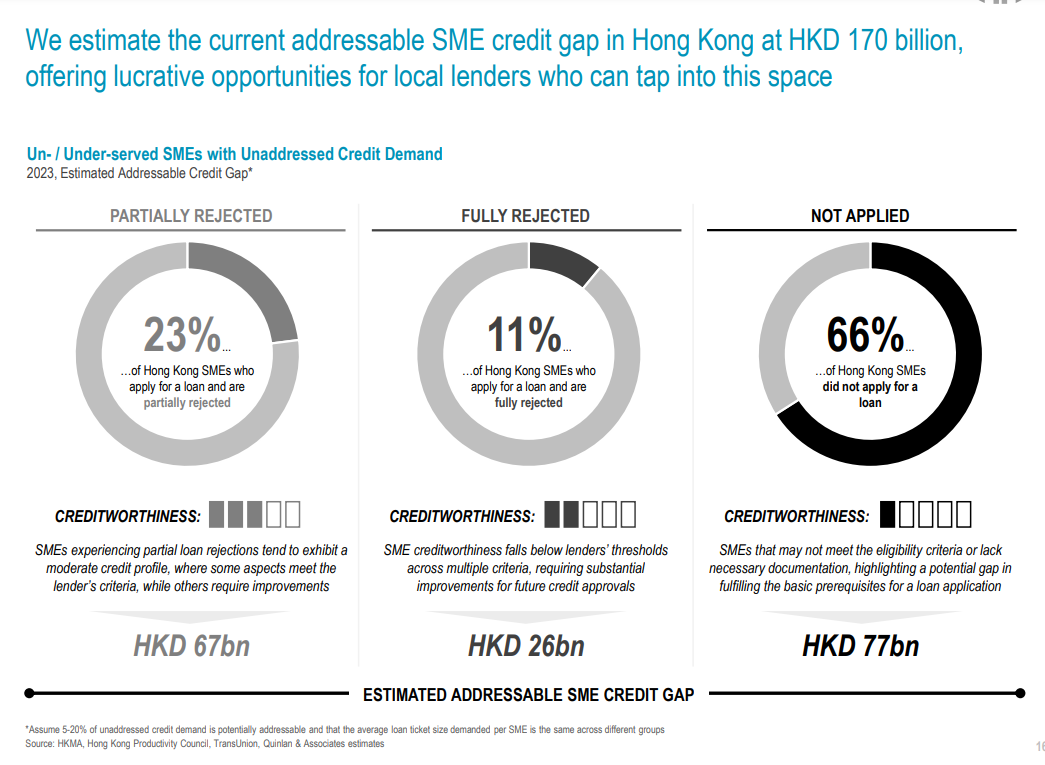
Between 2018 and 2023, only about 60 percent of Small and Medium Enterprises (SMEs) that needed credit applied for loans, and of these applicants, roughly 34 percent were either rejected or only partially approved.
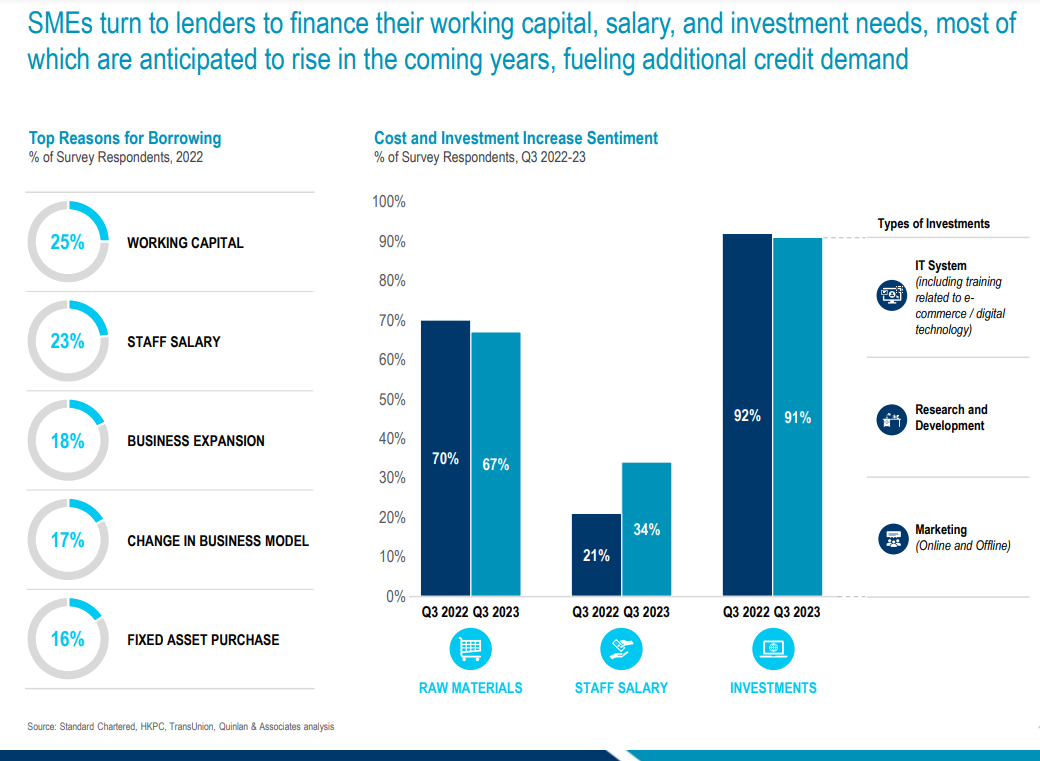
This data comes from interviews with over 30 established SMEs in Hong Kong, underscoring significant operational inefficiencies plaguing the SME lending landscape.
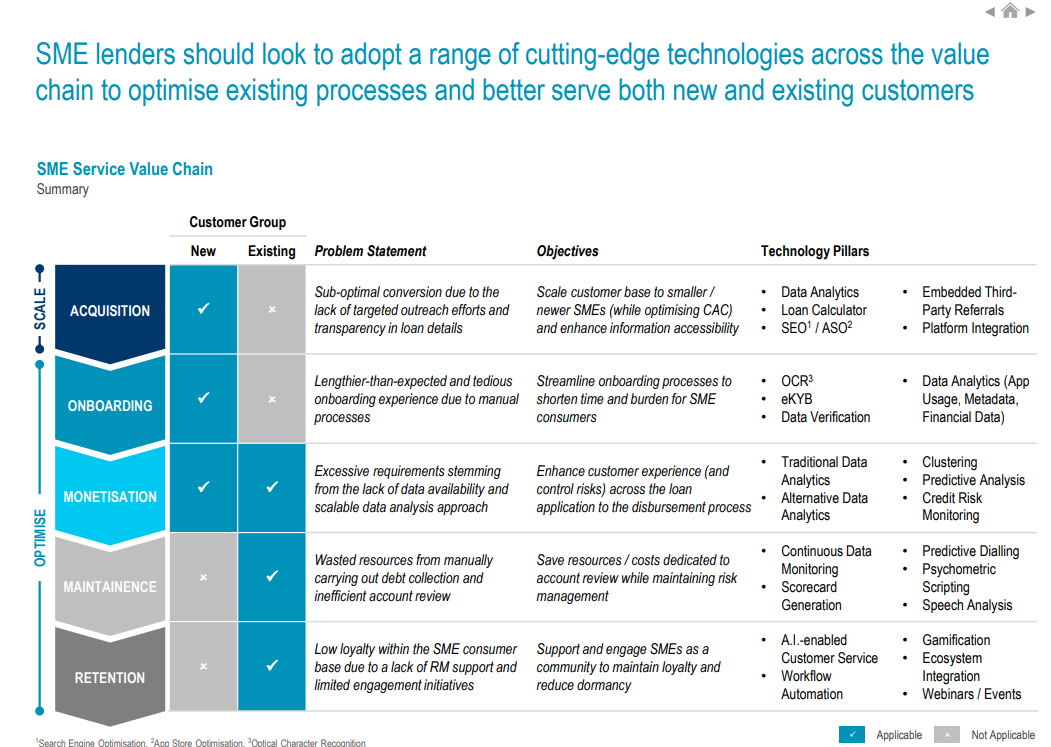
These pain points range from the initial acquisition phase, where SMEs face challenges in navigating through opaque loan options that lack precise information on approval timelines and documentation requirements, to onboarding processes marred by the absence of fully digital procedures, leading to extended timelines due to manual operations and constant back-and-forth communications.
The loan application stage is equally burdensome, with traditional banks insisting on physical paperwork and in-branch visits, accompanied by rigorous documentation, collateral requirements, and continuous follow-ups, which protract the process.
Maintenance of loans also poses issues, as lenders often conduct semi-annual reviews that necessitate further documents and face-to-face meetings to reassess the SME’s financial standing and adjust loan terms accordingly.
In addition, the loyalty phase reveals a significant gap in customer engagement. With minimal proactive interaction beyond transactions, SMEs are more inclined to switch lenders in pursuit of better terms or services. This landscape highlights a critical need for the banking sector to address these inefficiencies and improve the SME lending experience.
A HK$170 billion missed opportunity
Quinlan & Associates estimates Hong Kong’s persistent SME credit gap at a sizeable HK$170 billion in unmet financing demand. Plugging this gap requires a fundamental rethinking of current lending practices.
While technologies like Optical Character Recognition (OCR) can help streamline processes like onboarding, structural challenges around data and documentation availability remain.
The firm believes the long-term solution lies in “algo-based lending” – leveraging partnerships with data providers to build customised SME credit scoring models capable of rapidly pre-qualifying loans.
Rather than over relying on traditional financial documentation, these models would incorporate broader alternative datasets like payment history, online reviews, mobile usage patterns, and even psychometric tests.
This enables better assessing SME creditworthiness and uncovering previously underserved segments. By pre-qualifying cluster-based SME loans using such models, approval timeframes could shrink from weeks to days while maintaining robust credit risk management.
However, this bold new approach requires lenders to rethink their SME lending strategies and operating models from the ground up.
Charting the future of SME lending in Hong Kong
The journey towards revolutionising SME lending in Hong Kong through algo-based lending presents challenges and unparalleled opportunities.
Quinlan & Associates outline a strategic roadmap for lenders to harness this potential, emphasising the importance of identifying high-potential SME segments with significant credit demand.
Central to this transformation is selecting strategic data partners possessing relevant, non-traditional datasets that can enhance credit scoring accuracy. Clear, mutually beneficial partnership models and incentive structures are essential for fostering collaboration and innovation.
Developing and rigorously testing new, cluster-specific credit scoring models promises to tailor financial products more closely to SME needs. Adapting overall strategy and operational practices to institutionalise these advancements is crucial.
While challenging, the path to a reimagined SME lending landscape powered by data and algorithms is a necessity. By embracing cutting-edge technologies and the right partnerships, Hong Kong’s lenders can finally start addressing the city’s stubborn SME credit gap and better service this vital economic segment.
Featured image credit: Edited from Freepik
