Close Menu
    • Digital Transformation
    • Open Banking
    • Funding
    • Remittance
    • Regtech
    • Hong Kong Fintech Report
    • HK Fintech Startup Listing
    • China
    • Taiwan
    • Submit Press Release
    Facebook LinkedIn X (Twitter) YouTube RSS
    • About
      • About Fintech News Network
      • Contact Us
      • Work With Us
    • FNN Media Kit
    • Fintech Newsletter
    • Submit Press Release
    • Submit
      • Submit Press Release
      • Submit Startup
      • Webinar Inquiry APAC
    • HK Fintech Startup Directory
    Fintech Hong Kong
    part of Fintech News Network

    Fintech News Network

    LinkedIn Facebook X (Twitter) Instagram YouTube TikTok RSS
    Free Newsletter
    • Payments
    • Blockchain
    • Wealthtech
    • Virtual Banking
    • InsurTech
    • Lending
    • Report
    • Fintech Events
    Fintech Hong Kong

    Fintech News Network

    Home»Blockchain/Bitcoin»New IMF Paper Explores the Rise of Digital Money
    Blockchain/Bitcoin Mobile Payment

    New IMF Paper Explores the Rise of Digital Money

    Fintech News Hong KongFintech News Hong KongSeptember 2, 20194 Mins Read
    LinkedIn Facebook Twitter Telegram Copy Link Email
    IMF Digital Money
    Share
    LinkedIn Facebook Twitter Telegram Copy Link Email
    Free Newsletter

    Get the hottest Fintech Hong Kong News once a month in your Inbox

    As digital money grows in popularity, banks and credit card companies are facing increased competition from technology companies which are coming up with new ways to transact that are easier, more convenient and cheaper.

    GFTN Moving from Hype to Impact Preparing for an Agentic Future

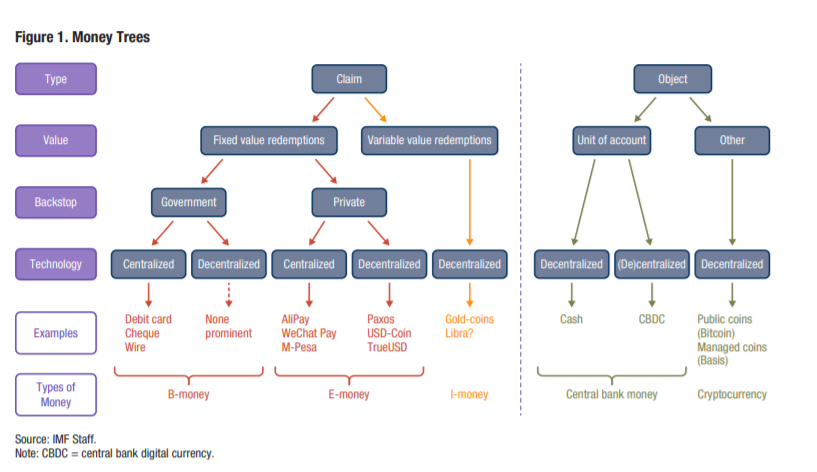
    Cash and bank deposits are battling with so-called e-money, electronically stored monetary value denominated in, and pegged to, a currency. These are offered by new private sector providers, and according to a paper by the International Monetary Fund (IMF), titled The Rise of Digital Money, their adoption could be rapid given their “attractiveness as a means of payment.”

    The paper notes that in countries including China and Kenya, e-money is already widely: 90% of Kenyans over age 14 pay with M-Pesa, and China’s WeChat Pay and Alipay currently process more e-money transactions than Visa and Mastercard combined.

    WeChat Pay
    WeChat Pay, via https://pay.weixin.qq.com/index.php/public/wechatpay

    Besides these services, blockchain-based forms of e-money are also popping up. Also referred to as “fiat tokens” or “stablecoins,” these include the likes of Gemini dollar, Paxos Standard, TrueUSD, and USD Coin by Circle and Coinbase.

    So far, e-money has taken off in just a few countries, but adoption could very well grow rapidly elsewhere, and there are several reasons for that.

    First, the paper cites the convenience of e-money. E-money is typically issued by companies that understand user-centered design and integration with social media. And according to the paper, these have managed to develop systems and solutions that are “better integrated into our digital lives [compared to] b-money (which currently is issued by bank) or central bank money.”

    E-money is also faster and cheaper than cash and bank deposits. Transfers in e-money are nearly costless and immediate, and thus often more attractive than card payments or bank-to-bank transfers, especially across borders.

    Furthermore, in countries where e-money is taking off, users trust telecommunications and social media companies more than banks.
    Digital Money IMF

    Another advantage of e-money is that it can incorporate technologies such as blockchain, which would allow for capabilities and features never seen before.

    For example, if assets like stocks and bonds were moved to blockchain-enabled infrastructure, blockchain-based forms of e-money would allow seamless payment of automated transactions; assuming these blockchains were designed to be interoperable.

    Additionally, the power of network effects to spread the adoption of these new services should not be underestimated, the paper says.

    “[The world’s big tech companies and fintech startups] are experts at delivering convenient, attractive, low-cost, and trusted services to a large network of customers,” it says.

    “User-centered design is second nature. They understand how people behave on social media and online. They can make payments integrate seamlessly. They did it once with social media; they could do it again with money, whether with an ‘e’ or even perhaps an ‘I’ in front of it.”

    The report also explores the effects of mainstream adoption of e-money on the banking sector and highlights the risks associated with these, including the potential creation of new monopolies, threats to weaker currencies, concerns about consumer protection and financial stability, and the risk of fostering illegal activities, among others.

    In the long run, large tech firms offering banking services will need to be regulated as banks and firms that offer the equivalent of investment funds, or broker-dealer services, would be regulated as such, the report says.

    The document also explores the emergence of i-money, short for investment money. I-monies are issued by private investment funds and represent a potential new means of payment, though whether or not the trend will take off remains unclear.

    I-money is equivalent to e-money, except for the fact that it offers variable value redemptions into currency, making it thus an equity-like instrument. I-money entails a claim on assets, typically a commodity such as gold or shares of a portfolio.

    Examples of gold-backed i-money are Digital Swiss Gold (DSG) and Novem. An example of i-money backed by a portfolio of assets is Libra, the cryptocurrency project announced by Facebook and members of the Libra Association in June.

    “I-money could be sufficiently stable to serve as a widespread means of payment,” the paper says. “However, as the transfer of i-money entails a transfer of ownership of securities, it may be subject to regulatory restrictions that could limit transactions across borders, for instance.”

    ReportSingapore Fintech Report 2026Read
    digital money e-money i-money International Monetary Fund (IMF)
    Share. LinkedIn Facebook Twitter Telegram Copy Link Email

    Author

    Avatar photo
    Fintech News Hong Kong
    • Website
    • Facebook
    • X (Twitter)

    Related Posts

    Project Ensemble Seeks Scale After Tokenised Deposits Go 24/7

    November 13, 2026

    UOB to Roll Out China QR Payments on TMRW by Year End

    November 12, 2026

    StanChart, Ant International Pilot Tokenised Fund Liquidity Facility

    November 11, 2026

    SOOHOO.IO, Suhyup Bank Test Tokenised Deposit FX Remittances on Partior

    November 11, 2026

    Animoca Brands Names Yat Siu CEO as Evan Auyang Takes Advisory Role

    November 10, 2026

    HashKey Exchange Now Offers SBI’s Tokenised Japanese Equity Fund

    November 6, 2026

    Hong Kong Fintech Week 2026 Main Conference Weighs Next Steps for AI

    November 5, 2026

    AMBR and HashKey Capital Partner on AI Agents in Finance

    November 5, 2026
    AI Sponsored Post

    Inside Huawei’s Fintelligent: Three Factories for Banking AI

    October 21, 2026
    Fintech Hong Kong Newsletter
    Subscribe to the most important Fintech Hong Kong News
    Follow Us
    • LinkedIn
    • Facebook
    • X / Twitter
    • Instagram
    • YouTube
    • TikTok
    Featured Fintech Reports

    Moving From Hype to Impact: Preparing for An Agentic Future

    S$9.98B in digital bank deposits. Top 10 funding rounds. Singapore Fintech Report 2026

    Thales: Executive Guide to Securing Digital Assets

    LexisNexis Solutions

    Payments Sponsored Post

    Fubon Bank (Hong Kong), ShopBack Launch Co-Branded Visa Platinum Card in Hong Kong

    Fintech News Hong Kong October 15, 2026
    Featured Webinar Replay

    How Fintechs Can Thrive in the Age of AI

    Is BNPL The Greatest Evil?

    Featured Fintech Videos

    Is BNPL The Greatest Evil?

    Hong Leong's New Card Is Forged in Fire And You Can't Apply for It

    Hong Kong Fintech Report

    Hong Kong Fintech Report 2025

    Whitepapers & E-Books
    State of Digital Trust: AI Governance Benchmark
    State of Digital Trust: AI Governance Benchmark
    Sumsub
    Upcoming Fintech Events
    Country
    Who Is Responsible When an AI Agent Makes a Payment?
    December 2, 2026
    Featured Online
    AVCJ Private Equity Forum Hong Kong 2026
    November 16, 2026
    -
    November 19, 2026
    Hong Kong
    -
    Central
    China Hi-Tech Fair (CHTF) 2026
    November 26, 2026
    -
    November 28, 2026
    China
    -
    Shenzhen
    Insurtech Insights Asia 2026
    December 2, 2026
    -
    December 3, 2026
    Hong Kong
    -
    Hung Hom
    Asian Financial Forum 2027
    January 26, 2027
    -
    January 27, 2027
    Hong Kong
    Promote Event View More
    FINTECH RESOURCES

    Navigations
    • About Fintech News Network
    • Contact Us
    • Media Kit
    • Work With Us
    • Fintech Hong Kong Newsletter
    • Submit a Fintech Hong Kong Press Release
    • Fintech Events Hong Kong & China
    • Fintech HK Startup Report
    • Submit Your HK Fintech Startup
    • Privacy Policy / Disclaimer
    Other Fintech News Network Publications
    Fintech News Hong Kong
    Fintech News Singapore
    Fintech News Malaysia
    Fintech News Philippines
    Fintech News Network Indonesia
    Fintech News Network Australia
    Fintech News Switzerland
    Fintech News Baltic
    Fintech News Nordics
    Fintech News America
    Fintech News Middle East
    Fintech News Africa
    Get Informed

    Subscribe to Updates

    Subscribe to the most important Fintech Hong Kong News

    LinkedIn Facebook X (Twitter) YouTube RSS
    • About Fintech News Network
    • Contact Us
    • Media Kit
    • Work With Us
    • Fintech Hong Kong Newsletter
    • Submit a Fintech Hong Kong Press Release
    • Fintech Events Hong Kong & China
    • Fintech HK Startup Report
    • Submit Your HK Fintech Startup
    • Privacy Policy / Disclaimer
    © 2015 - 2026 Copyright Finanzpro GmbH. All Rights reserved.

    Type above and press Enter to search. Press Esc to cancel.