
In the past decade, the market for retail digital payments has witnessed heightened competition across various economies, which the Bank for International Settlements (BIS) attributes to rapid digitalization, the emergence of cutting-edge technologies, and the entry of new players.
In a new paper released in July, the organization analyzes the market’s evolution over the last ten years and assesses the current competitive landscape.
The report underscores the profound transformation that has occurred in the retail digital payment market. This market is now characterized by intensified competition in both the user-facing front as well as in the back end.
The retail digital payments landscape
Notably, mobile payment apps have gained significant popularity worldwide. These apps offer consumers a wider range of choices for both in-person-to-person (P2P) and person-to-merchant (P2M) payments, introducing greater convenience and flexibility.
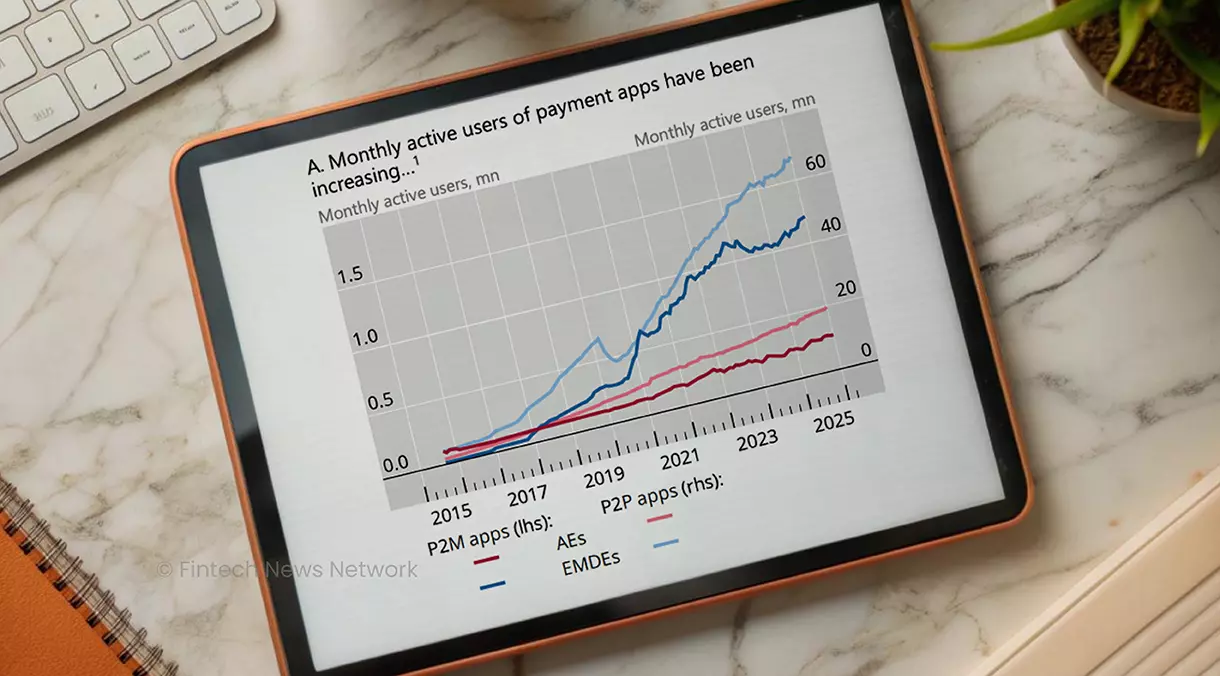
According to BIS analysis, the number of monthly active users of payment apps has experienced a remarkable surge over the past decade, reaching approximately 1.3 million users for P2M apps, and about 90 million users for P2P apps in 2025.

Increased competition is also evident in back-end retail payment systems, supported by fast payment systems (FPS) that offer alternatives to card networks. However, some established players, like global card networks Mastercard and Visa, continue to dominate the market, maintaining high revenue and profit margins despite heightened competition.
In 2025, Visa and Mastercard’s net revenue reached approximately US$45 billion and US$41 billion, respectively, marking a significant increase from less than US$15 billion a decade ago. Profit margins grew as well, rising from about 40% and 30% for Visa and Mastercard, respectively, in 2015 to 50% and 45%, a decade later, according to BIS.

New dynamics
In this evolving landscape, new dynamics and strategic behaviors are emerging, challenging market competition, the report stresses. One notable aspect is the nature of many markets for front-end payment systems, such as P2M payments. These markets are oftentimes two-sided, involving interactions between two distinct user groups.
This means that a wallet, app or card’s value hinges on the acceptance of merchants and the usage of consumers. Consequently, significant network effects can arise, organically creating barriers for new entrants and reinforcing the market power of incumbents and players with substantial resources.
At the same time, strategic behavior by market participants in the front end can also stifle competition. For example, many digital payment methods rely on third-party providers for essential technologies, such as near field communication (NFC) at the point-of-sale (POS). Hence, front-end competition can be constrained by those providing hardware.
A relevant example is Apple’s historic practice of restricting NFC chip access on iPhones exclusively to Apple Pay and Apple Wallet. This restriction effectively blocked third-party payment apps, limiting iPhone users to using only Apple’s own mobile payment services.
In the European Union (EU), Apple agreed to open its “Tap to Pay” iPhone payment system in July 2024 after the Commission formally launched an antitrust investigation in 2020. This investigation revealed that Apple “abused its dominant position” in markets for mobile wallets on iOS devices, breaching EU laws. This restriction effectively limited competition in the mobile wallets market on iOS.
In response to the restriction lift and the opening of third-party developer access, Vipps MobilePay, a major Nordic mobile payment and digital wallet solution serving around 12.4 million users across the region, launched an alternative to “Tap to Pay on iPhone” in December 2024.
“Tap with Vipps” is a contactless mobile payment feature that lets users pay in stores using NFC technology. It works on iPhone and Android, functioning as an alternative to Apple Pay, Samsung Pay and Google Wallet. By the end of 2025, 1.05 million Vipps MobilePay users had activated “Tap with Vipps”.
Fragmentation and the lack of interoperability add to these challenges. For example, prior to regulatory interventions, the biggest payment apps in China, namely WeChat Pay and Alipay, were incompatible with each other and with other payment apps.
However, in 2021, China’s Ministry of Industry and Information Technology (MIIT) told bigtech companies, including Alibaba, Tencent, and ByteDance, to make their “walled gardens” accessible to competition, stressing that blocks were disrupting market order, creating unfair competition, and infringing upon the rights and data security of users. Consequently, major tech companies introduced interoperability between digital payment platforms.
Differences among payment service providers (PSPs) in data access and usage capabilities can pose additional threats to competition in front-end payment markets. While fintech companies may have superior data analytics tools, they often lack the scale of banks, which hold vast amounts of detailed financial data.
Furthermore, participants can exploit market power in adjacent markets to distort competition through bundling, cross-selling, or subsidizing products and services. For example, in Kenya, Safaricom’s market dominance in the mobile money market has been sustained due to its control of the underlying telecom infrastructure.
According to the latest statistics from the Communications Authority of Kenya (CA), Safaricom’s mobile money platform M-Pesa holds 89.1% of mobile money subscriptions in the country. Additionally, the company commands approximately 68.9% of total mobile subscriptions, and 62.7% of the mobile broadband market.

China’s retail digital payment ecosystem
China boasts one of the world’s most advanced retail digital payment ecosystems, having leapfrogged payment cards to embrace QR code and mobile payments methods on a large scale. In urban areas, cash usage has become rare, and cards are frequently integrated into mobile wallets for direct mobile device transactions.
In 2025, payment apps accounted for 87% of POS value in China, surpassing the global average of 37%, according to a recent report by Worldpay. This made China the largest user of digital wallets globally. Conversely, cash accounted for just 4% of POS spending in 2025 and 1% of e-commerce spending in the same year.
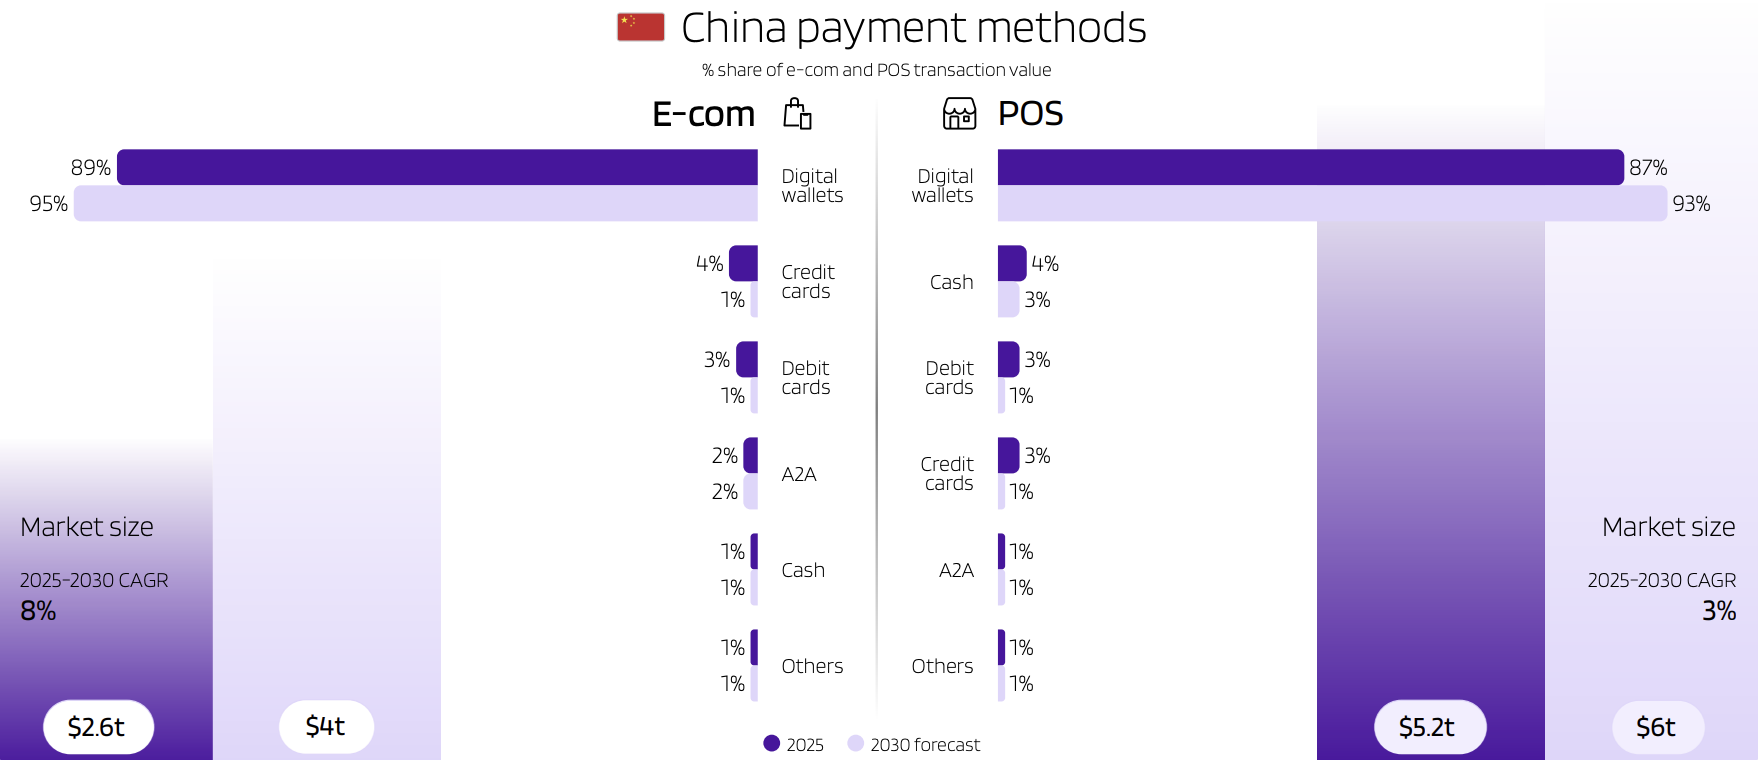
Alipay and WeChat Pay are the dominant players in the domestic market, cited respectively by 85% and 73% of consumers surveyed by Worldpay. These services collectively account for over 90% of China’s mobile payment market, boasting 1.4 billion and 935 million active users, respectively, according to some reports.
Alipay and WeChat Pay have also gained widespread acceptance overseas, and are now accepted by select merchants in many destinations popular with Chinese consumers. These destinations include Japan, Singapore, Malaysia, and parts of Europe.
Featured image: Edited by Fintech News Hong Kong, based on image by wahyu_t via Magnific
