
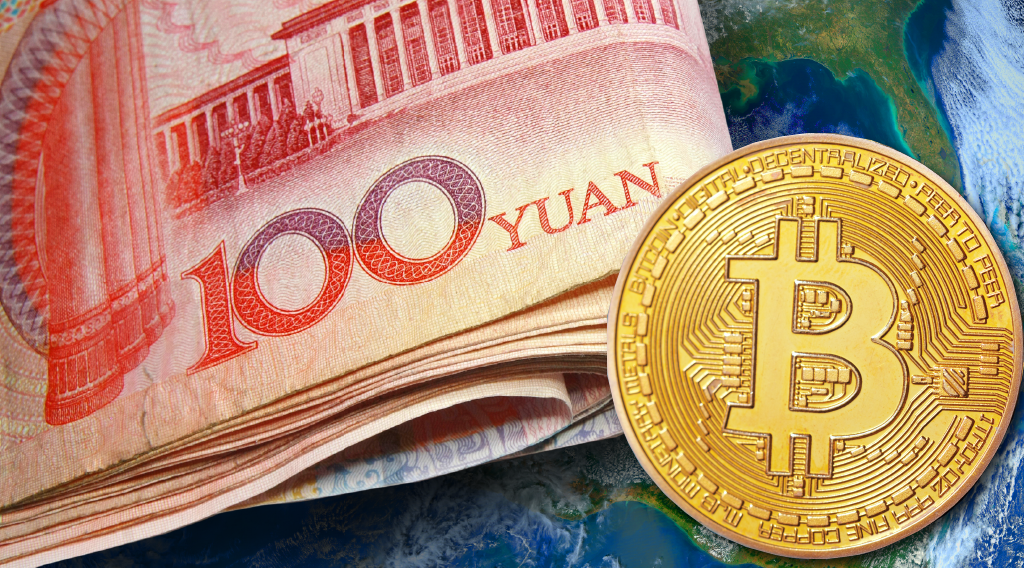
Blockchain and cryptocurrencies have been all the rage these past years. Now even central banks are looking to launch their own digital currency.

So-called central bank digital currencies (CBDCs) differ from traditionally digital currencies like bitcoin and ether in the sense that the latter are not issued by the state and lack the legal tender status declared by the government.
Over the past years, governments and central banks have been studying and testing CBDCs to realize the many positive implications these could contribute in the areas of financial inclusion, economic growth and technology innovation.
While the Bank of England is often cited as one of the first to initiate a global discussion on the prospects for the introduction of a CBDC, it is actually the People’s Bank of China (PBOC) that has been amongst the pioneers on the topic.
The PBOC was in fact the first major central bank to study digital currencies in 2014, and after receiving approval from the State Council, the central bank began working with market institutions on creating a CBDC.
Speaking at an event in China in August, Mu Changchun, deputy director of the payments unit at the PBOC, said its researchers have been hard at work since 2018 to complete the systems needed to support the digital yuan offering and that it is “close to being out.”
But why is the PBOC rushing to get the digital yuan up and running? And why is it so interested in launching a China’s own version of digital currency anyways?
We’ve compiled some the key ideas and reasons formulated by experts, academics and industry participants on why the PBOC is so eager to launch its very own China digital currency.
Curbing the dominance of tech giants
In China, mobile payment is a big thing and the US$17 trillion industry is dominated by tech giants Tencent and Ant Financial, which have a combined 90%+ market share. However, neither Ant Financial nor Tencent are banks, and so must be a 100% backed by reserves.
“The result is that these digital wallets store enormous cash reserves … Since Alipay and WeChat Pay are not regulated as banks, it creates huge financial risk for consumers,” wrote Henry He, a serial entrepreneur, token economics evangelist, and security and IP routing expert, in a guest post on VentureBeat.
“China’s DC/EP (Digital Currency Electronic Payment) product will disrupt these closed systems.”
By launching its own sovereign digital currency, the PBOC could tighten its grip on the country’s deposit pool and help banks catch up with their mobile payment business, according to Cindy Wang, an analyst at DBS Group Research.
“Currently, banks are under pressure to retain their deposit base because, with the money market funds distributed by third-party payment providers like Alipay or Tencent, some of the idle money held in mobile payment accounts are leaked out of the banking system into the hands of fund managers,” Wang told the South China Morning Post.
“With banks’ loan-to-deposit ratio rising, if banks continue to lose their deposit base it will be difficult for them to keep up with their lending, so through the digital currency the PBOC hopes to divert some of the deposits back to the banking system.”
Capital control
According to the PBOC’s Mu, the development of a digital yuan could help protect China’s foreign exchange sovereignty as commercial applications of digital currencies are rapidly expanding. And the fact that US tech giant Facebook has recently unveiled its Libra stablecoin initiative, has put a sense of urgency to the task.
“Why is the central bank still doing such a digital currency today when electronic payment methods are so developed?” Mu said, quoted by Reuters.
“It is to protect our monetary sovereignty and legal currency status. We need to plan ahead for a rainy day.”
Facebook’s push to introduce Libra could strengthen the US dollar’s dominance, and weakening China’s capital controls. According to Wang Xin, the head of the PBOC’s research bureau, that could have “economic, financial and even international political consequences.”
Traceability
Experts and analysts have also said that a digital currency would allow China to get total traceability over all economic transactions, thus avoiding the problems associated with cash, such as crime and submerged economy. That’s “all very much in line with Beijing’s policy of rigid population control,” said Enrique Dans, professor of innovation at IE Business School.
Echoing Dans’ statement, He Zhiguo, a professor at the University of Chicago Booth School of Business, told Forkast.News in a recent interview:
“The fundamental economics reason behind it is that [the government] understands there’s a lot of good part of having a digitalized asset where you can trace where you’re coming from, where you go, and make the settlement super quick … there’s a lot of legal issues in China with fraud.”
Though the PBOC’s Mu has said that the central bank has put effort to balance anonymity and privacy, and the need to fight financial crimes, user identities will likely be tied to individual wallets, reports Bloomberg. Additionally, banks may need to submit daily information on transactions to the central bank.
Staying at the forefront of innovation
Another possible reason for China’s push to launch a national digital currency might be Beijing’s desire to stay at the forefront of technology.
“If Beijing still doesn’t allow us to innovate [on cryptocurrency], we are lagging behind for the next 200 years. We’re back into the Opium War,” He said.
“[Beijing doesn’t] want to lag behind the frontiers of technology, but all of a sudden, there’s a brand new idea [of cryptocurrency and Facebook’s Libra] that also seems to be getting support from other parts, not just these Chinese crypto people, but also from the US.”
Research and innovation regarding digital currencies was mentioned in the grand plan to turn the tech hub of Shenzhen into “one of the leading cities in the world in terms of economic strength and quality of development” by 2025. Shenzhen has been flagged by the Chinese government for trials of the new digital currency.
More broadly, Beijing has pledged to transform the mainland into a global powerhouse in innovation by 2050.
